What is the market overview and industry significance of the Military Multi Domain Operations Software Market?
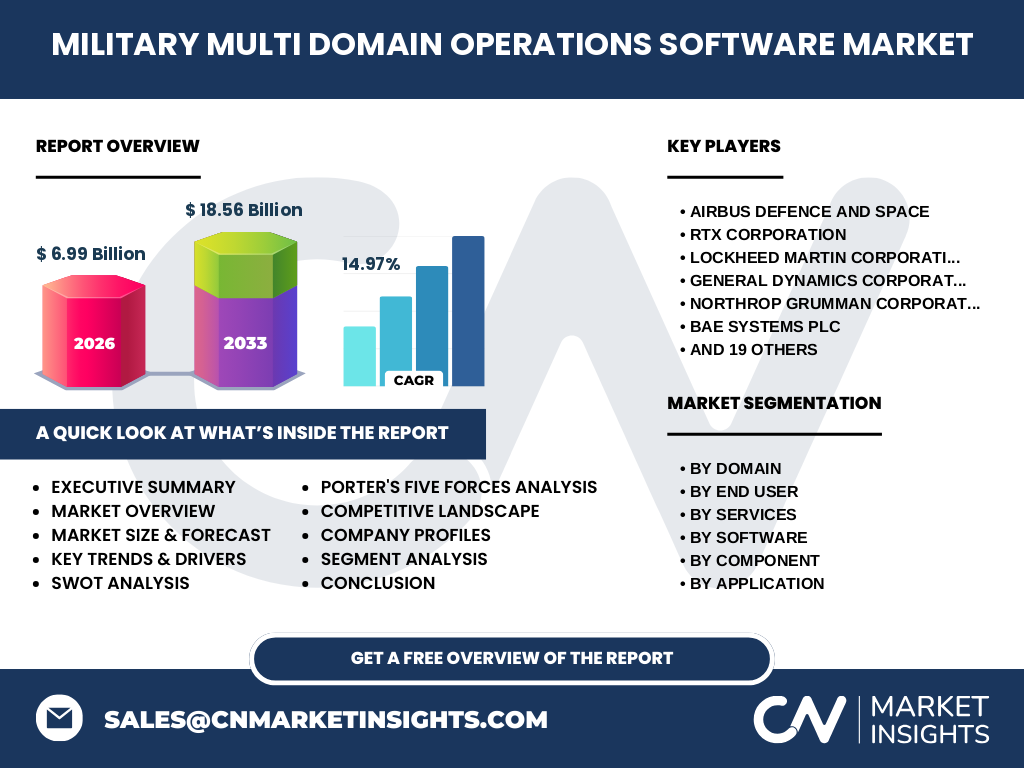
Our analysis indicates that the Military Multi Domain Operations Software Market is valued at $6.99 Billion in 2026, establishing a critical foundation for modern defense ecosystems. This market encompasses advanced software suites orchestrating seamless tactical engagement across Land, Sea, Air, Cyber, and Space domains, directly mandated by the U.S. Department of Defense's Joint All-Domain Command and Control (JADC2) initiative.
What are the key market drivers, restraints, challenges, and opportunities shaping the Military Multi Domain Operations Software Market?
The primary structural driver is the proliferation of edge sensors demanding real-time data fusion, contrasted with severe accreditation bottlenecks and stringent Department of Defense Information Network (DoDIN) cybersecurity compliance. Market opportunities heavily favor developers of cloud-based analytics platforms capable of bridging legacy tactical data links with modern commercial infrastructure.
Emerging trends and growth patterns in the Military Multi Domain Operations Software Market
The data suggests a radical pivot toward software-defined defense, led by venture-backed disruptors like Shield AI and Anduril Industries Inc.. These innovators are deploying autonomous edge-processing algorithms that bypass traditional satellite communication bottlenecks, creating decentralized resilience during contested electromagnetic spectrum operations.
How did the COVID-19 pandemic affect the Military Multi Domain Operations Software Market and shape its recovery trajectory?
While pandemic-era supply chain disruptions temporarily stalled hardware-reliant integration milestones, they paradoxically accelerated software procurement. Defense agencies rapidly shifted budgets toward zero-trust remote architectures and virtualized training environments, permanently restructuring the acquisition lifecycle toward rapid agile software deployment.
Competitive Benchmarking and Strategic Dynamics
Market concentration features a dual ecosystem where traditional prime contractors like RTX Corporation and Lockheed Martin Corporation leverage deep system integration dominance, while agile software specialists such as Palantir Technologies Inc. and C3.ai Inc. provide foundational data fusion and analytics layers.
Executive Summary: High-Level Synthesis of Key Findings
Based on our comprehensive research, the Military Multi Domain Operations Software Market is set to expand from $6.99 Billion in 2026 to reach $18.56 Billion by 2033 at a robust CAGR of 14.97%. This explosive trajectory is propelled by urgent requirements for cross-domain orchestration amid rising geopolitical friction.
Market Forecast and Trajectory from 2027 to 2033
Our growth modeling confirms that the sector will maintain an exceptional 14.97% CAGR throughout the 2027-2033 forecast window, culminating in a total market valuation of $18.56 Billion by 2033. Accelerated procurement cycles by Joint Forces commands will drive this steep upward inflection.
Segmentation Analysis of the Military Multi Domain Operations Software Market
The market breaks down across several distinct vectors: By Domain (Land, Sea, Air, Cyber, Space, Cross Domain); By Software (Command And Control Systems, Mission Planning, ISR, Data Fusion); By Component (Software, Services); By Deployment (On Premises, Cloud-Based); and By Application (Command, Control, Logistics, Cyber Operations).
Geographic Distribution and Regional Performance
North America dominates global consumption due to massive baseline defense outlays by the Pentagon and prominent primes like Northrop Grumman Corporation and L3Harris Technologies Inc. Meanwhile, the Asia-Pacific region exhibits the fastest acceleration driven by regional naval modernization and digitized command restructuring.
In-Depth Regional Review of Operational Constraints
European market dynamics are shaped by stringent interoperability mandates from the European Defence Agency (EDA), favoring firms like Thales Group, Leonardo S.p.A., and Hensoldt AG. Conversely, North American deployments prioritize proprietary JADC2 compliance and resilient multi-orbit satellite integration.
Company Profiles and Strategic Positioning
Industry leaders occupy distinct strategic niches: BAE Systems plc and General Dynamics Corporation dominate mission-critical naval and land integration, while specialized innovators like Hadean, Rebellion Defense Inc., and Helsing pioneer hyper-scalable simulation and AI-enabled decision advantage tools.
Porter's Five Forces Analysis of Competitive Intensity
Supplier power remains moderate given specialized defense-grade microelectronics dependencies, whereas buyer power is heavily concentrated among sovereign defense ministries. Threat of substitution is low due to specialized security accreditations, but competitive rivalry is fierce among platform integrators and AI scale-ups.
SWOT Analysis: Internal Capabilities and External Pressures
Key strengths include deep domain expertise and proprietary intelligence fusion algorithms; primary weaknesses involve bureaucratic procurement lags. Major opportunities stem from commercial AI dual-use adoption, while persistent threats include sophisticated state-sponsored cyber espionage against supply chains.
Value Chain Analysis from Code to Deployment
The value chain flows from foundational raw telemetry inputs and semiconductor silicon through advanced algorithmic data fusion engines, culminating in secure deployment via cloud or tactical edge systems maintained by specialized contractors like Booz Allen Hamilton Holding Corporation and Leidos Holdings Inc.
Investment Insights and High-Potential Growth Pockets
Our analysis indicates that investors should target specialized middleware developers and automated test accreditation software providers. Companies capable of bridging legacy tactical radio waveforms with modern cloud fabrics will capture outsized valuation premiums during the 2027-2033 forecast window.
Conclusion and Strategic Key Takeaways
The Military Multi Domain Operations Software Market represents a generational shift in defense technology. With a projected leap to $18.56 Billion by 2033, success depends on modular software architectures that seamlessly integrate legacy hardware with next-generation artificial intelligence.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining defense budget authorizations, trade registry data, primary stakeholder interviews with defense procurement officials, and secondary macroeconomic indicators from multilateral security organizations to ensure high-fidelity market sizing.
Scope of the Report and Boundary Parameters
This report covers global software and services expenditures dedicated to multi-domain military operations across 2026 to 2033. Hardware manufacturing, kinetic munitions, and unclassified commercial enterprise software sectors are explicitly excluded from this market boundary.
Recent Developments, Partnerships, and Strategic Acquisitions
Recent market velocity is punctuated by strategic partnerships between defense primes and AI pioneers, alongside venture investments in firms like BigBear.ai Holdings Inc. and Kongsberg Gruppen ASA, focusing on automated threat recognition and sovereign cloud tactical nodes.